


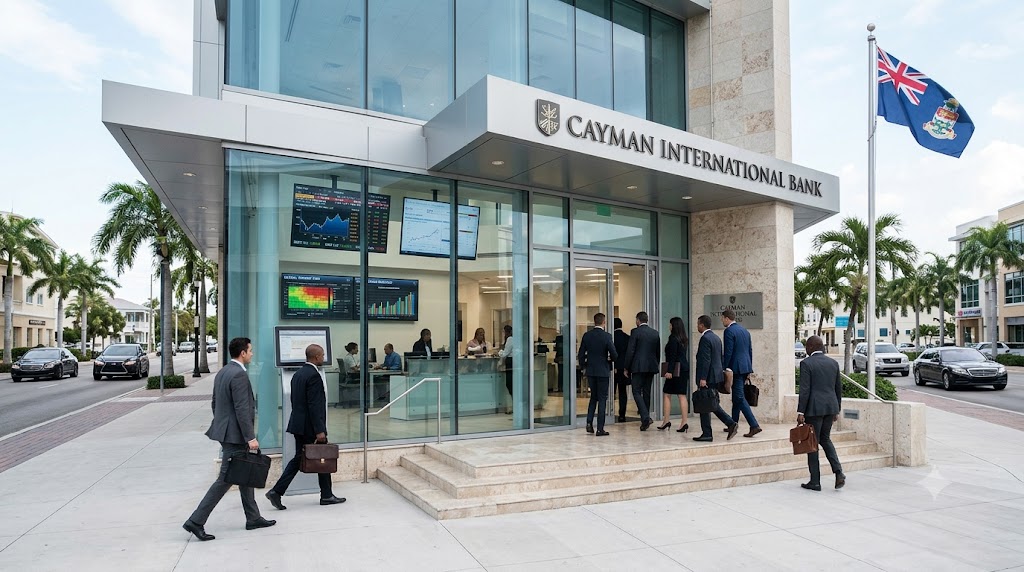
Banks and other deposit-taking institutions in the Cayman Islands are facing new regulatory requirements after the Cayman Islands Monetary Authority (CIMA) introduced guidance requiring them to prepare formal financial recovery plans.
Announced on November 2, 2026, the new Rule and Statement of Guidance on Recovery Planning gives affected institutions two years to submit plans explaining how they would respond to severe financial stress.
The plans must address potential crises such as sudden bank withdrawals, global economic shocks, rogue trading and reputational damage. Institutions must also provide a board-approved action plan setting out the steps they would take to protect their operations and financial stability.
CIMA will assess whether the proposed plans are sufficient. If a recovery plan is considered inadequate, the regulator can require an institution to maintain higher capital reserves, potentially increasing operating costs.
The new requirements are intended to strengthen the resilience of the Cayman Islands financial sector and reduce the risk that failing institutions would need public financial support.
For banks, credit unions and building societies, the two-year deadline means regulatory planning and financial risk management will become an important business priority.
Comments (0)
Sign in to join the conversation.